01
First-time buyers
You've never done this before, and nobody explains it properly. I'll walk you through what you can actually afford, what pre-approval really means, and what happens between the offer and the keys.
I'm Greice, a mortgage broker in Calgary. I read the whole contract with you — not just the rate — so you know exactly what you're signing before you sign it.
Licensed in Alberta · Mortgage Connection · English, Portuguese and Spanish
Four situations I work with every week. Find yours — the question is never whether your case is unusual, it's which lender is built for it.
You've never done this before, and nobody explains it properly. I'll walk you through what you can actually afford, what pre-approval really means, and what happens between the offer and the keys.
Limited Canadian credit or employment history doesn't have to be a dead end. There are lender programs built for newcomers, and work permit holders can often buy with as little as 5–10% down. I'll tell you what's realistic for your timeline — in English or Portuguese.
If your income doesn't show fully on paper, structuring is everything. I present business-for-self income the way lenders actually assess it, instead of stopping at the one bank that read your file too narrowly.
A renewal offer isn't always your bank's best rate — it's often just their easiest one to send you. I'll shop it before you sign. The same applies if you're refinancing, consolidating, or buying a second property.
Three steps. No cost to start, and no obligation at any point.
A conversation, not an application. You tell me where you are and what you're trying to do; I tell you honestly what's possible and what isn't. Nothing is submitted anywhere.
I put your file together the way lenders assess it, then take it across prime, alternative and private lenders to find the one built for your situation — comparing the whole mortgage, not just the rate.
I explain every term before you commit. Then I track your renewal date, watch for rate changes that could help you, and I'm the first call when your plans change.
The rate is only one line of the contract.
Penalties, prepayment privileges, portability, how the payout is calculated — a lower rate can hide a much more expensive exit. I run the full comparison, and if your bank's offer really is the better deal, I'll tell you so. On most traditional mortgages the lender pays my commission, so there's no cost to you.
I was a lawyer in Brazil, and then a university professor. Both jobs were really the same job: taking something complicated and making it make sense to the person in front of me.
I've been in Canada for eight years. I know what it is to arrive with no credit history, no Canadian references, and a stack of documents nobody will explain to you. That experience is why I work the way I do.
Today I'm a mortgage broker with Mortgage Connection in Calgary. I don't sell rates. I explain contracts, in whichever of my three languages you're most comfortable in, until you genuinely understand what you're agreeing to.
My brokerage app, with the numbers you can run yourself before we ever talk. No sign-up, no sales call attached.
Run your own numbers before we ever talk.
Regulated Canadian immigration consultants (CICC licence R513223) — work and study permits, permanent residence and family sponsorship, in English, Portuguese and Spanish.
Exclusive discount
CAD$10 off an immigration consultation with code GREICEGALHARDO
A community connecting Brazilians in Canada with each other and with the local businesses that serve them — services, events and people who have already made the move.
The questions I'm asked most often, answered the way I'd answer them on a call.
Usually not. On most traditional mortgages, the lender pays my commission — so there's no cost to you. Alternative or private financing sometimes involves a fee, and if that applies to your file, I disclose it in writing before you commit to anything.
Because the rate is only one line of the contract. I compare the whole mortgage — penalties, prepayment privileges, portability, how the payout is calculated. A lower rate can hide a much more expensive exit. I'll run the full comparison, and if your bank's offer really is the better deal, I'll tell you so.
Often, yes. A decline usually just means you didn't fit one lender's specific rulebook — not that you're unmortgageable. I structure your file properly and shop it across prime, alternative and private lenders to find one built for your situation. Every mortgage is still subject to qualification and lender approval.
This is exactly where structuring matters most. I present business-for-self income the way lenders actually assess it, and match you with lenders comfortable underwriting non-traditional income — instead of stopping at the one bank that read your file too narrowly.
Yes — limited Canadian credit or employment history doesn't have to be a dead end. There are lender programs built for newcomers, and I'll walk you through exactly what's realistic for your timeline, in English or Portuguese.
Pre-qualified is an estimate based on what you tell me. Pre-approved means I've verified your documents and a lender has committed to a rate and amount, subject to the property. If you're about to start house-hunting, you want to be pre-approved, not just pre-qualified.
You can, but you don't have to. A renewal offer isn't always your bank's best rate — it's often just their easiest one to send you. I'll shop it before you sign anything.
Yes — a work permit alone doesn't rule you out. A number of lenders will finance work permit holders, often with as little as 5-10% down, especially with a stable job and enough time remaining on your permit. The exact terms shift depending on your specific status and timeline, so I'll walk you through exactly what you qualify for before you start house-hunting.
No. I track your renewal date, watch for rate changes that could benefit you, and I'm the first call when your plans change — buying again, refinancing, adding to the family. This is a relationship, not a transaction.
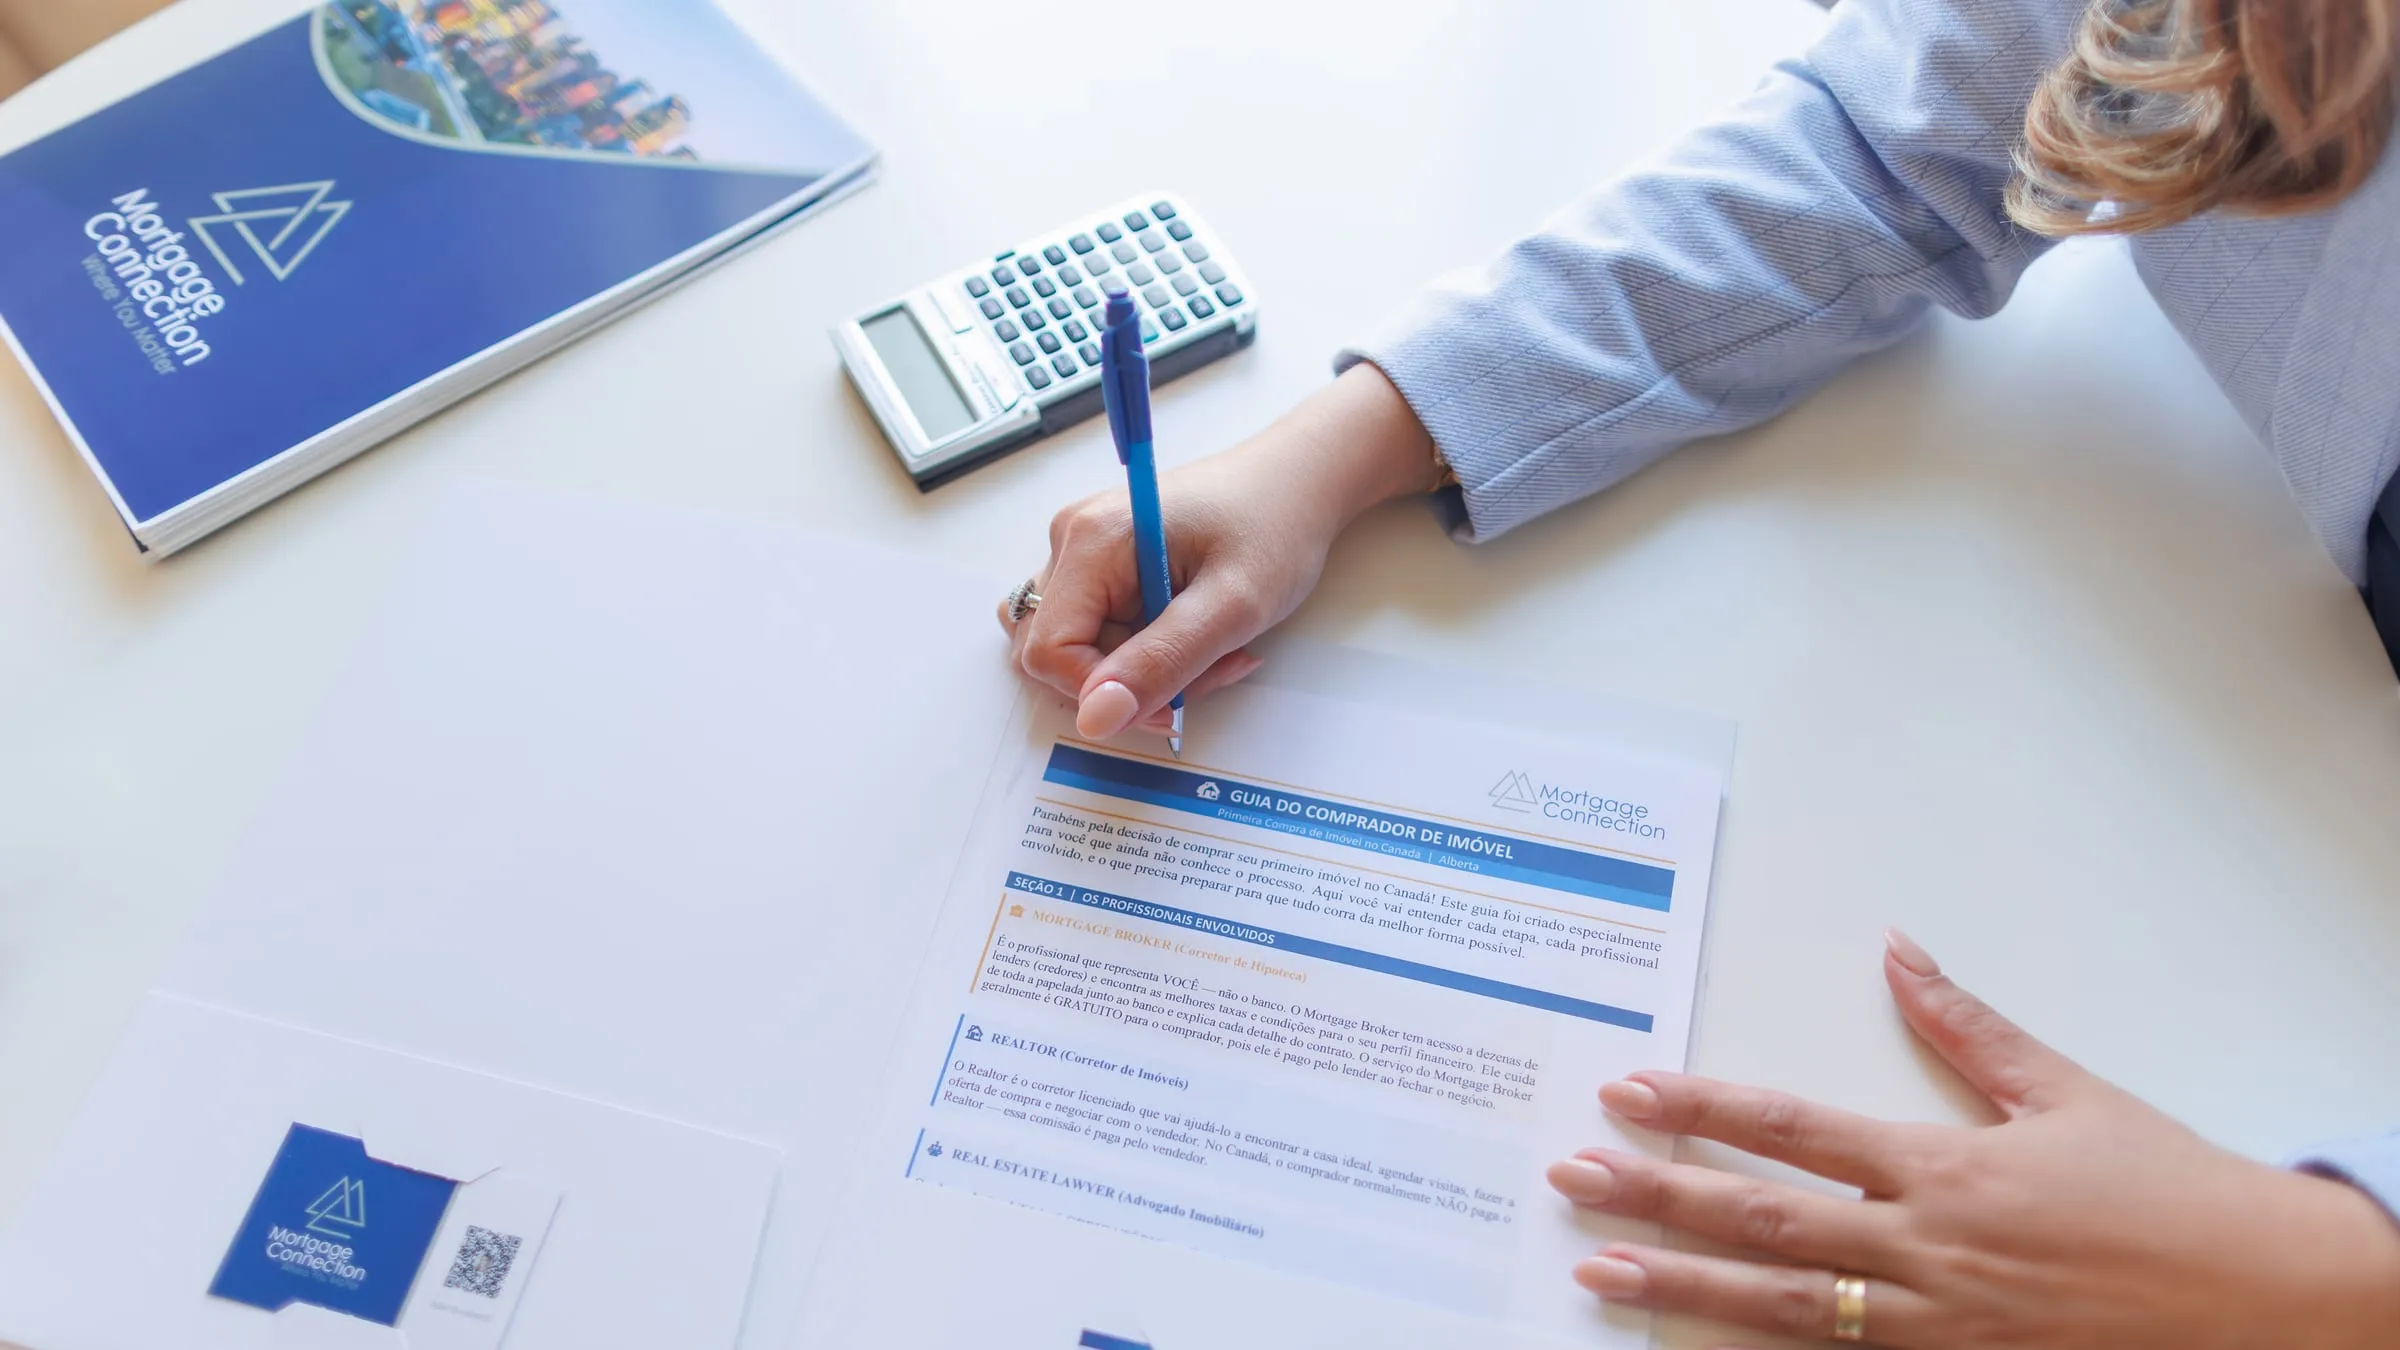
Two guides I put together for my clients, free to download. Read them at your own pace, then bring your questions to a call.
Who does what — broker, realtor, lawyer, inspector — the step-by-step from pre-approval to keys, and the government programs first-time buyers can use.
greicemortgage
The PDF asks for it when it opens. Type it in lowercase.
What changed between 2024 and 2026, why you don't have to renew with your current lender, and how to compare offers before you sign.
Pick a time in my calendar. It's free, with no obligation.
No Microsoft account needed — just continue as a guest.
A first conversation costs nothing and commits you to nothing. Message me, book a call, or send the form — whichever you're most comfortable with.